Scott Galloway’s complaint that our parents are living too damn long is a line about houses, and the Federal Reserve’s inheritance data, published years before the clip, shows the queue he meant.
Scott Galloway teaches marketing at NYU’s Stern School of Business and has spent years writing that America’s fortunes are mostly handed down. It is a small irony, then, that his most travelled sentence on inheritance is a joke that reads worst on its own. A professor’s line about mortality makes a better clip than a professor’s line about housing, and so the clip outran the argument. Read against the documents, the argument is the more interesting of the two, and the less comfortable. Our rule here is narrow. We use what he said, what he has written in his No Mercy / No Malice essays, and one official figure for when Americans inherit, laid side by side.
A Prof G Pod clip carries the line
Galloway says “Quite frankly our parents are living too damn long” in a resurfaced clip from The Prof G Pod, which was already circulating on X by 10 November 2026. The subject around the sentence is property. His complaint is that inheritance has become the only means by which the young get a house, and he calls what that does inside families an unhealthy dynamic. The show has not said which episode the clip comes from. Its feed that week carried the historian Eliza Filby, author of Inheritocracy, on why getting ahead increasingly depends on your parents’ wealth. Whatever the source, the topic was in the air at the show that autumn, and the clip travelled without its context, as clips do.
A few seconds of a man saying something blunt about the elderly is the material X was built for, and it was received in that spirit. The longer conversation, about who can afford a front door and at what point in life, compresses badly. It needs a second sentence, and sometimes a third, and the clip had room for one. What survived the edit was the punchline. The set-up stayed on the cutting-room floor.
His target was the system, not his parents
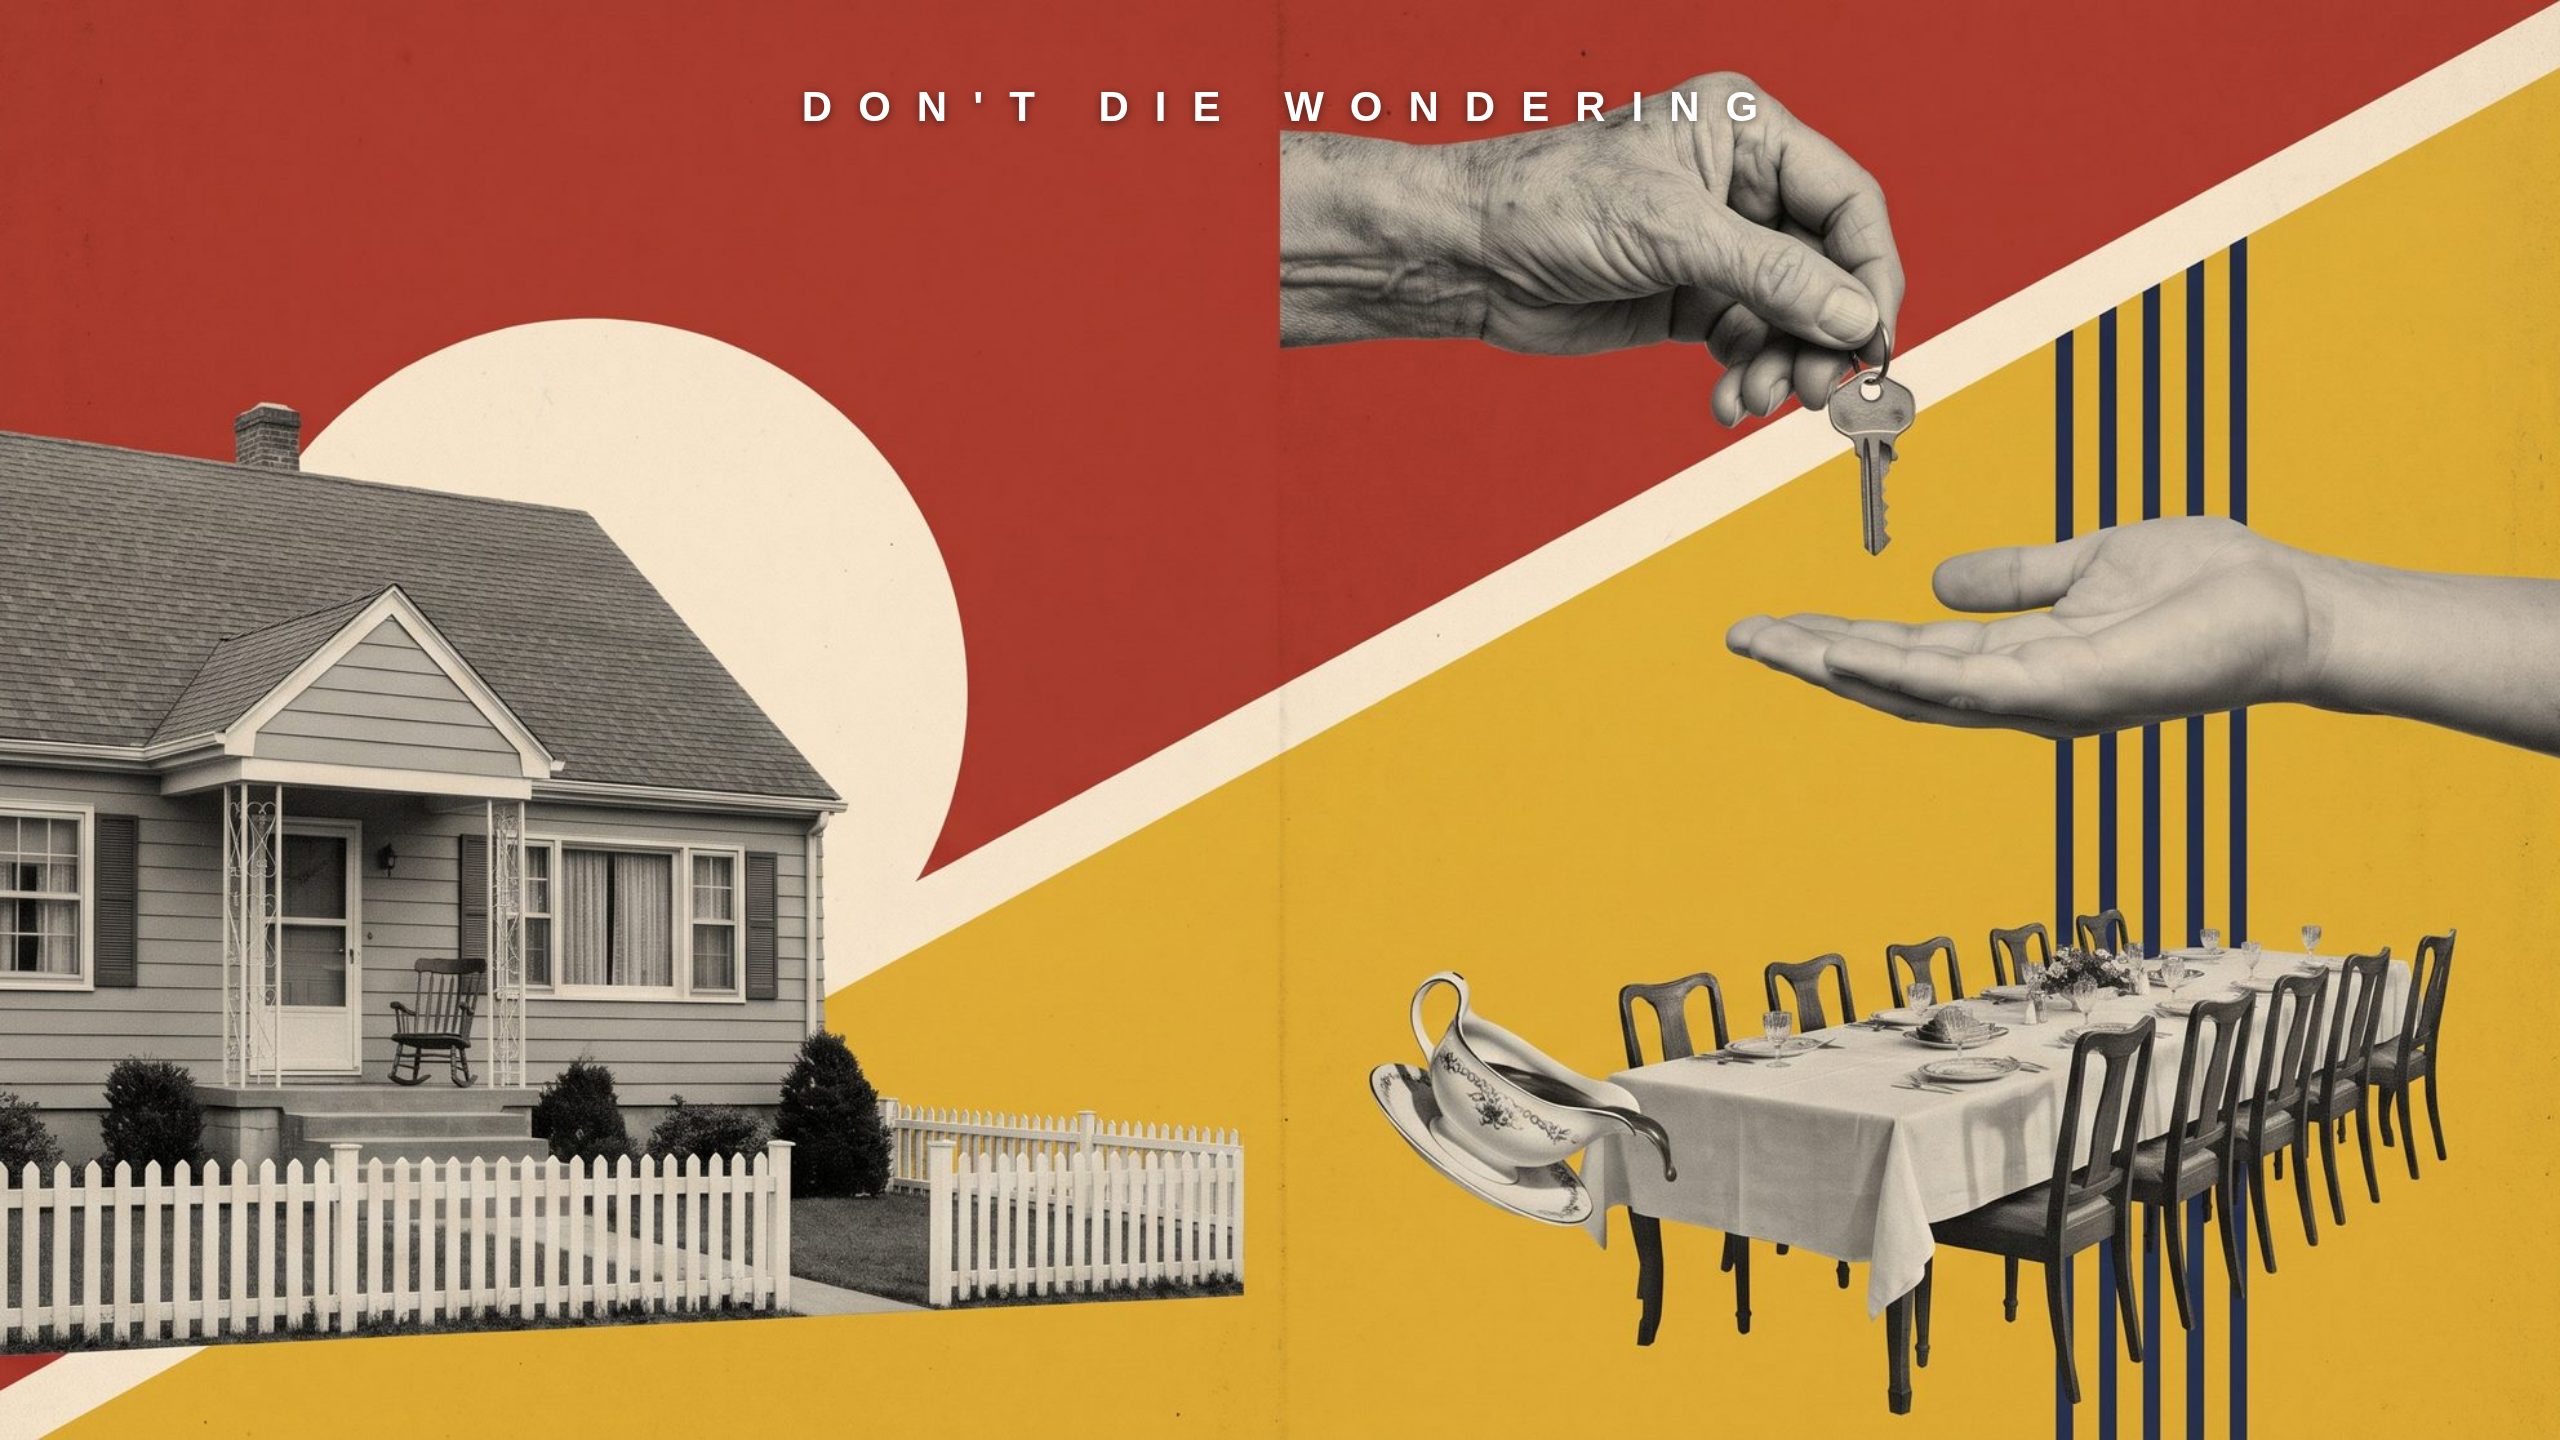
DDW’s reading is that Galloway was criticising a system in which a young adult’s first front door depends on parental wealth. He was not wishing anyone gone. The case against that reading is easy to make, because the words are the words, and “living too damn long” lands at a Sunday lunch like a dropped gravy boat. But his essays frame the whole subject as a transfer of wealth between generations and the timing of it. An unhealthy dynamic is a phrase about how a family arranges its money while everyone is still at the table. A man who simply wanted his elders out of the way would have no use for an argument about housing. Galloway has one, and he has written it out several times, at length.
There is also the matter of his register. DDW’s reading of the Galloway method, on the show and on the page, is that he says the outrageous version first and the careful version second. The provocation gets the attention, and the figures do the work once the attention has been got. A clip keeps the first half of that and drops the second. Anyone who has listened past the opening minutes of an episode will recognise the move. Anyone who has only seen the clip will hear something closer to a confession.
The Fed dates inheritance to late middle age
The Federal Reserve Board’s FEDS Note of 1 June 2018, built on the Survey of Consumer Finances, finds that inheritance receipt peaks at around age 60 for all income groups. The Fed’s explanation is plain arithmetic. It points to generational age gaps of around 20 years and lifespans of around 80. That figure is a peak, the age at which receipt is most common, and it is neither an average nor a median. The note dates from 2018, so it describes a pattern and is not a 2026 statistic.
For a family hoping the old house will fund a child’s first one, the timing is the whole difficulty. By that stage of life the heir usually has a house, or has given up on one, and is thinking about a pension rather than a deposit. Money that lands then may well be passed straight down again, to a grandchild, which only moves the problem along a generation. The phrase “for all income groups” matters too. Wealthier families do not, on the Fed’s evidence, receive earlier; they receive more, at the same unhurried moment. On the Fed’s clock, the money for a starter home arrives when its heir is well past starting.
Two million households a year receive the cheque
The same note gives the scale. On average, that many American households receive either an inheritance or a substantial gift in a given year, and the Fed counts the two together. The measure leaves out transfers to surviving spouses. A widow who keeps the family house therefore sits outside the count, and the children who later inherit it from her sit inside it. DDW’s reading of the two Fed findings together is that Galloway’s queue is real, orderly and slow. Money moves down it one generation at a time, and nobody jumps ahead because a mortgage broker is waiting.
The pairing of inheritance and gift is the most useful thing in the note for anyone with a family to arrange. A substantial gift is an inheritance with the timing changed by choice, and it is the one lever in the whole business that a family controls. Death sets one date; a parent can set another. Galloway’s unhealthy dynamic lives in the gap between the two, between the parent who could give now and the child who is quietly waiting for later. Neither of them is likely to raise it over lunch.
Most Americans will inherit nothing, his essay says
In “The 1% Next Door”, his No Mercy / No Malice essay from 2026, Galloway puts the generational wealth transfer now under way at $110 trillion, “according to one estimate”. He then splits the cake. The top 2 per cent of US households, he writes, are expected to pass $62 trillion to their heirs, and four in five Americans will not inherit anything at all. Read beside the Fed’s timing, this is the harder half of his argument. A slow queue is one thing. A queue that ends at an empty table for most of the people standing in it is another, and it is the version he puts in print.
That inheritance tsunami won’t be evenly distributed.
The hedge in “according to one estimate” is honest, and worth respecting: he does not pretend the headline sum is a census. The sum itself flatters the idea of a great handover, the kind of phrase that fills conference programmes. The split tells you most Americans will watch the handover rather than take part in it. That is the context the clip lost. A complaint about parents who live too long only makes sense for the minority with something to wait for, and Galloway’s own essay says so.
Under-40s now hold a thinner slice of wealth
His earlier essay “War on the Young” sets out the shift in two snapshots. In 1989, he writes, Americans under 40 held 12 per cent of household wealth against 19 per cent for the over-70s. Today, by his figures, the under-40s hold 7 per cent and the over-70s 30 per cent. He read the essay aloud as an audio edition of the newsletter, in the season he was promoting his book The Algebra of Wealth, so the argument has been in his listeners’ ears for a long while. The clip simply delivered it in the register of a man who has had a long week.
Two snapshots decades apart is a blunt instrument, and he uses it bluntly, for effect. The effect is the point. A generation holding a shrinking slice is a generation that waits, and the waiting falls hardest on the years when a house would change a life. The same essay explains why the clip found an audience so quickly: the people most likely to share it are the people his figures describe. The wealth sits with the people who have lived longest, and in the essay the rest is economics.
He credits most big fortunes to family capital
In “Shoulders of Giants”, another No Mercy / No Malice essay, Galloway writes that only about a third of the wealthiest Americans came from poor, working-class or middle-class families with no significant family capital. The other two-thirds, in his phrase, “stood on the shoulders of a giant”, and he names the giant generational wealth. Put that beside the Fed’s peak age and the shape of his complaint is complete. A fortune made from nothing is the exception in his own count. Inherited capital is the rule, and under the rule the capital arrives late.
For much of DDW’s readership this is less a finding than a description of the room. The giant is rarely mentioned at dinner and is always present, in the school fees, the first flat, the introduction that came through an uncle. Galloway’s contribution is to put a proportion on it and print the proportion under his own name. His joke about parents is a joke about that delay, made by a professor who has spent years charting who receives family money and when.
The sensible plan assumes the money arrives late
The obvious follow-up is when, and whether, an inheritance will buy the house. The documents answer it without much mercy. Americans who inherit do so most often in late middle age, the Fed’s data shows, and on Galloway’s own reading most Americans never inherit at all. Visa’s economists count $36 trillion passing from boomers to younger heirs over the next 20 years, a vast sum moving at the pace of a family, which is slowly.
The quieter implication sits with the families on the other side of the queue. If the money arrives late by default, the only way to make it arrive early is to decide to, which is what a gift is, and which the Fed already counts beside inheritance as if the two were siblings. That decision belongs to the parents, not to the professor or the clip. Galloway’s advice, across his essays, is for the young to build without waiting for it. His clip was rude about the timetable. The Federal Reserve had published it in 2018, with better manners.
Read Next: Seven Facts Behind Dave Portnoy’s Ex-Wife Arrangement in 2026