Seven people founded Anthropic in January 2021, each sold an identical parcel of shares when it listed, and together they still command most of the votes, which is exactly how a new fortune ought to be arranged.
The best number in the Anthropic IPO is a small one, and it appears seven times. Read the Profile, 19 November 2026, puts the shares sold by each co-founder at 3,378,378. The seven are Dario Amodei, Daniela Amodei, Tom Brown, Jack Clark, Jared Kaplan, Sam McCandlish and Christopher Olah. Seven parcels of that size come to 23,648,646, which is the exact figure Anthropic’s pricing release gives for shares sold by selling stockholders. By our count, every share sold by a selling stockholder came from one of those seven people, in equal measure.
The rest of the deal was large in the conventional way. Anthropic priced at $83 a share on 18 November, above the range it had set, and CNBC reported the same day that the upsized offering raised $81.3 billion, more than SpaceX’s record listing in June. The stock began trading on the Nasdaq Global Select Market on 19 November under the ticker ANT. The offering was due to close on 20 November.
DDW’s view is that the founders got the important part right. In the listing itself they sold together, in the same amount, and kept control of what happens next. That control is now the thing most worth arguing about. It should stay where it is.
A special share keeps the votes with seven
The arrangement is laid out in the final prospectus. The seven co-founders are initially the sole members of something called the Founder LLC, which holds a special share. On its own, that sounds like the kind of detail a lawyer adds at five o’clock on a Friday. Its effect is spelled out in the prospectus filed for European investors. On beneficial ownership as of 30 September 2026, the co-founders’ combined voting power after the offering is about 11.2% without the Founder LLC and 61.3% with it.
One share therefore moves seven people from a respectable minority to a commanding majority. It is the most consequential share in the building, and nobody can buy it on Nasdaq.
The seven are not absentee landlords. The final prospectus names Daniela Amodei as President and Chairperson of the board, and the S-1 names her brother Dario as Chief Executive Officer. It lists Tom Brown as Chief Compute Officer, Jared Kaplan as Chief Science Officer and Sam McCandlish as Chief Architect, and says Jack Clark leads the Anthropic Institute. A brother and sister run the company and chair it, and five colleagues from the founding year hold senior titles. Older fortunes would recognise the shape at once.
An old fortune learns early that the income can be shared and the decisions cannot.
Public buyers paid knowing the votes stayed home
The strongest case against all this is easy to make. Public shareholders supplied the bulk of the capital and received a minority of the say. A company worth arguing over as a public asset is, in practice, steered by seven people whose votes far outrun what their shares alone would give them. Governance purists have spent decades warning about structures like this, and some of their warnings have come true elsewhere.
The answer is in the documents. The voting split was printed in plain figures in a prospectus that anyone could read before buying. Investors read it and still paid above the range. Forbes reported on 19 November that the stock opened at $111.50 and closed its first day at $97.17, more than 17% above the issue price. Nobody was ambushed. A buyer who wanted equal votes for equal money had every chance to stay away, and the order book suggests few did.
There is a second answer, and it concerns the selling. The usual worry about founder control is that founders take the votes and the exit at the same time, keeping the steering wheel while quietly emptying the boot. CNBC read the prospectus as giving the seven $1.96 billion in proceeds between them, a large sum by any civilian measure. It was split equally, sold at one price, on one day, by everyone who holds the special share. The listing was not the whole story: according to Forbes, Dario and Daniela Amodei disclosed earlier tender-offer sales of $157 million in June 2025 and $4.7 billion in April 2026. In the offering itself, if you are going to hand seven people the votes, that is the pattern of behaviour you would hope to see from them.
Four-fifths of the equity is pledged away
The detail that settles it for us comes from the final prospectus. Each co-founder pledged to dedicate 80% of personal equity in Anthropic to philanthropic causes. It is a stated intention, written into a document the Securities and Exchange Commission keeps on file. Readers who have sat through enough family meetings will know that the gap between a pledge and a cheque can be wide. The pledge is still there, in print, with all seven names attached.
That pledge changes what the control is for. A dynasty keeps the votes so that the shares can pass down intact, along with the house, the board seat and the right to be disagreeable at Christmas. A founder who has promised four-fifths of the equity away is holding the votes for some other reason. DDW’s reading is that the special share is better understood as custody than as inheritance. The people who made the promise keep the means to see it through.
It also explains why the dispersed public shareholder is a poor substitute. Index funds do not sign philanthropy pledges. A shareholder base of millions has many virtues, but steadiness of purpose is not reliably one of them.
New money, borrowing old habits
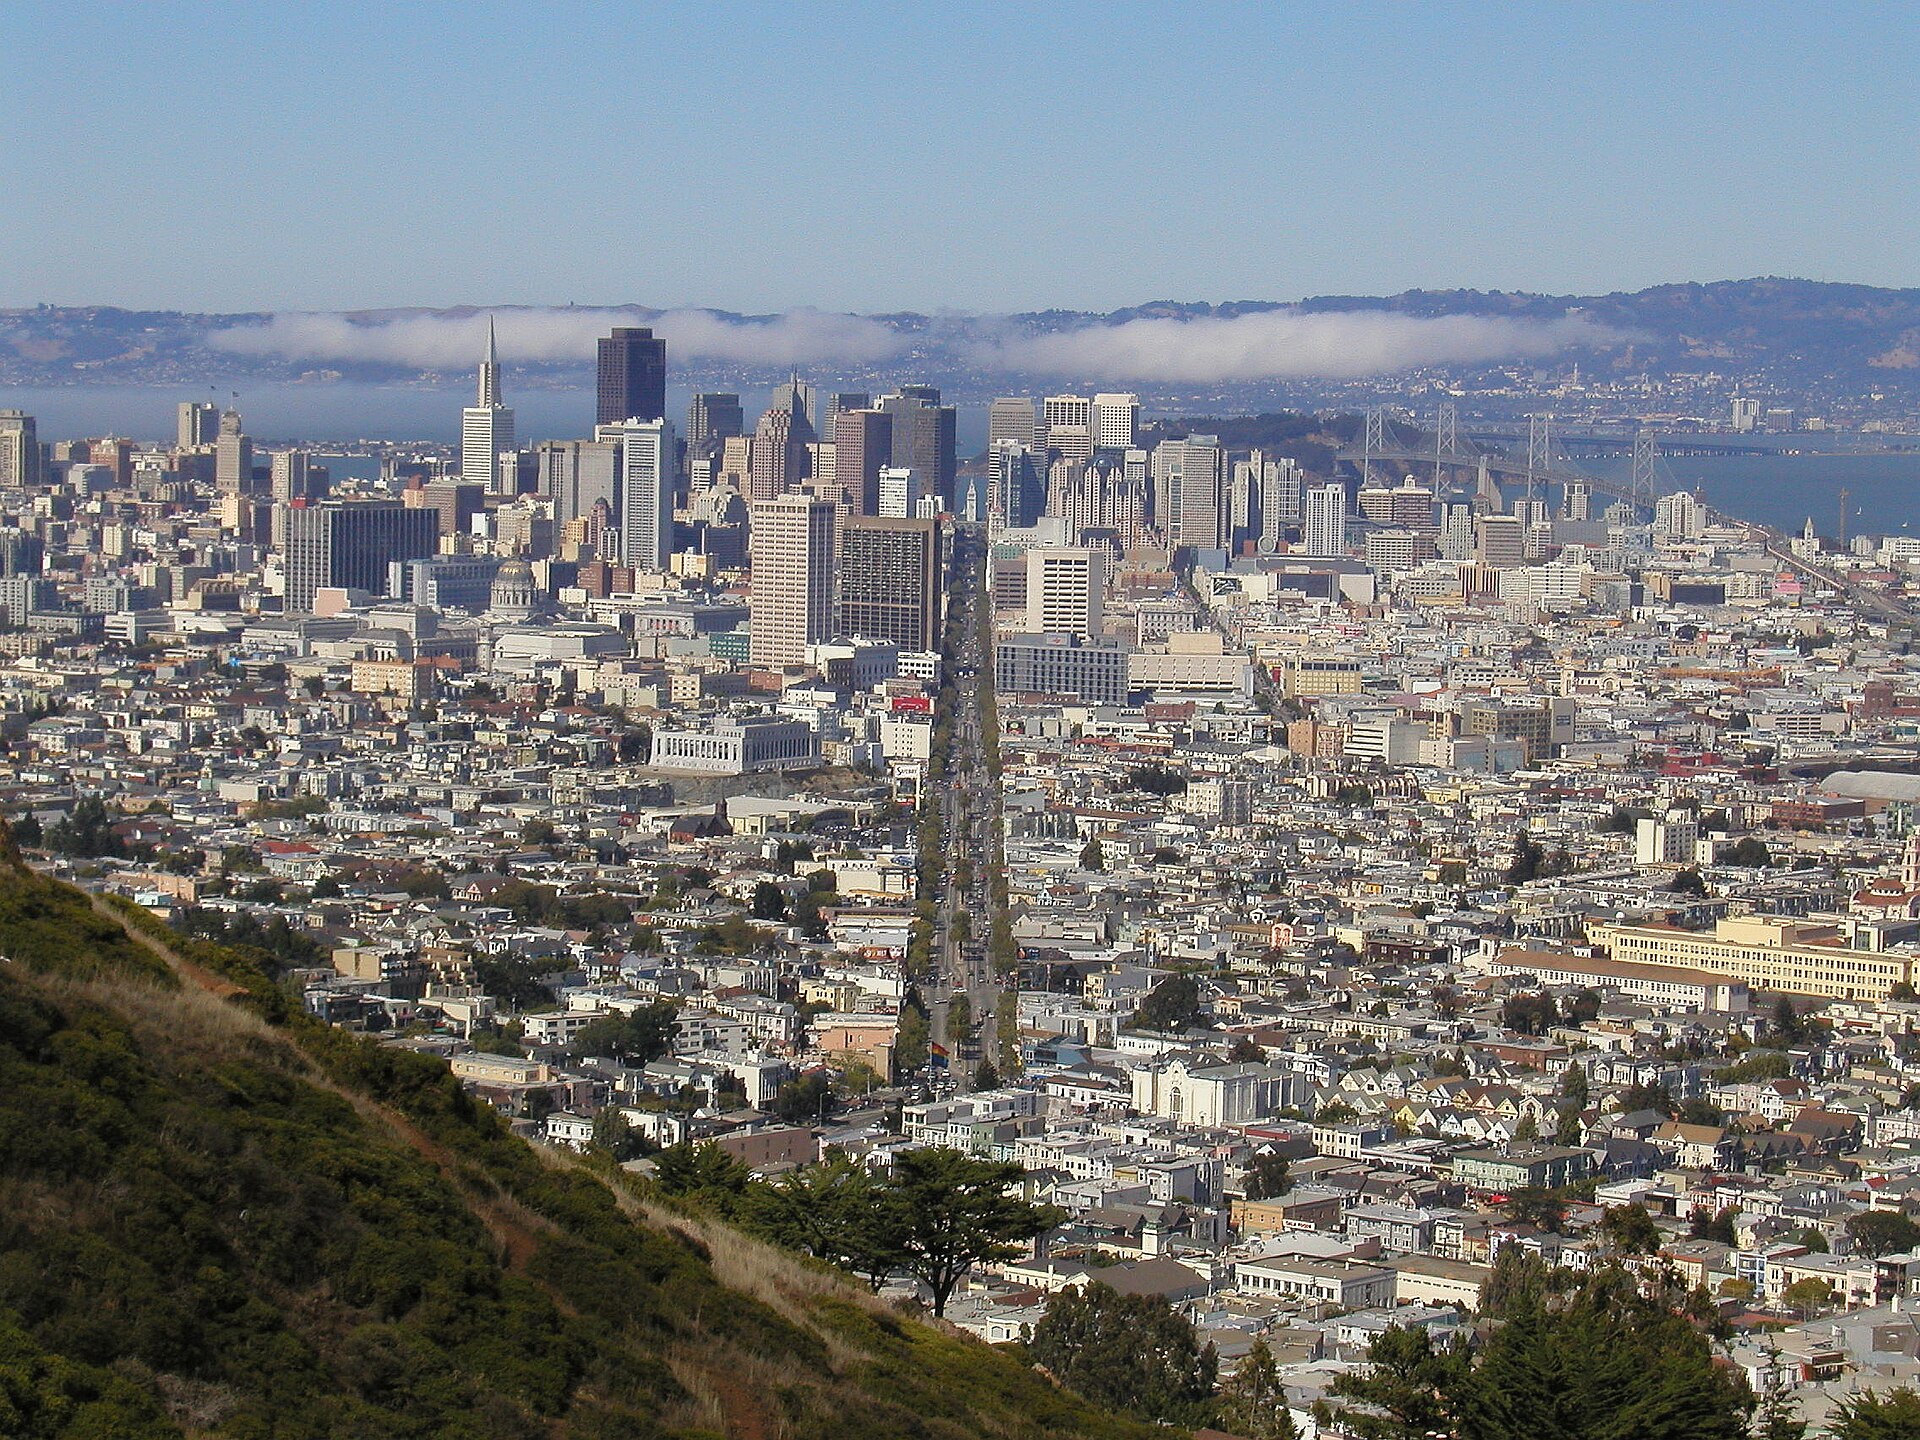
San Francisco has a new fortune, and its paperwork has a sense of humour. The S-1 filed on 26 October gives the company’s principal executive office as 548 Market Street PMB 90375, a mailbox number. Anyone expecting a marble lobby with the family name in brass will be disappointed. The money is real and the votes are concentrated. The front door, for official purposes, is a private box.
That modesty of address is appealing, and slightly beside the point. What makes this a fortune worth watching is the structure underneath. Seven people built a company, sold equal slivers of it on the same day, and kept the decisions among themselves through one share and a limited liability company. The public was told all of this in figures and paid a premium anyway.
The alternative was a founding team that sold more and kept less, leaving a company of this size to be steered by whoever held the largest block on any given morning. That might have been tidier in a governance seminar. It would have been worse for the promise in the prospectus, and worse for anyone who wants that promise kept.
The votes belong with the seven who signed it. Leave them there.
Read Next: Harrison Ford’s $150 a Week Deal, Explained for 2026
Cover photograph: TechCrunch via Wikimedia Commons (CC BY 2.0).